
Categories
Burlington County, Camden County, Gloucester County, Home Buying Tips, Housing Guide, New Jersey Real Estate, Real Estate Guides, South Jersey Real EstatePublished September 22, 2026
The Hidden Cost of Special Assessments for South Jersey Condo and Townhome Buyers
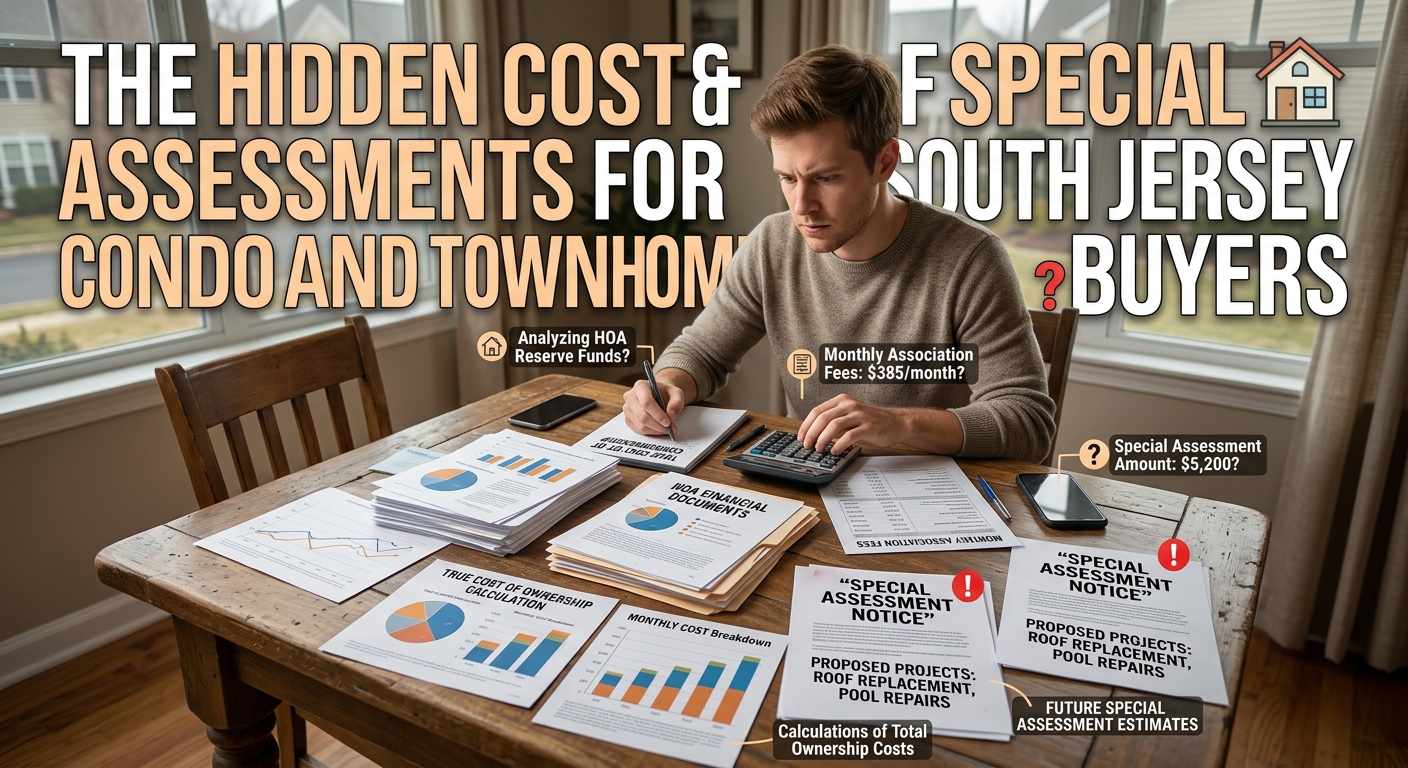
The listing price looks affordable.
The monthly association fee seems manageable.
The community has a pool, landscaping, exterior maintenance, and other amenities you like.
Then you discover one more number:
A $6,000 special assessment.
Or $10,000.
Or $20,000.
Suddenly, the property doesn't look quite as inexpensive as it did when you first saw the listing.
For South Jersey condo and townhome buyers, this is one of the costs that can be easy to overlook because it doesn't always appear in the same place as the purchase price or regular monthly association fee.
And unlike a predictable monthly expense, a special assessment can represent a significant additional financial obligation.
New Jersey recognizes that condominium and other common-interest communities involve assessments and fees beyond ordinary state and local taxes. The state's Department of Community Affairs also provides information concerning association financial records and owner access to those records.
As Mary Murphy of The Murphy Group explains:
“Buyers need to look beyond the monthly association fee. The real question is whether there are current or anticipated expenses that could materially change the cost of owning the property.”
🏘️ What Is a Special Assessment?
A special assessment is an additional charge imposed by a condominium, homeowners, or other community association to fund expenses that aren't covered—or aren't fully covered—by the association's regular budget.
The money may be needed for major work such as:
- Roof replacement
- Exterior repairs
- Siding
- Roads or private driveways
- Drainage improvements
- Structural work
- Building systems
- Common-area renovations
- Emergency repairs
- Major maintenance projects
The exact authority, amount, payment schedule, and allocation method depend on the association's governing documents and applicable law.
That's why buyers should never assume that all associations handle assessments the same way.
💰 1. The Purchase Price Isn't Always the Full Cost
Imagine two South Jersey townhomes:
Townhome A
Purchase price: $400,000
Monthly association fee: $300
Townhome B
Purchase price: $390,000
Monthly association fee: $300
Special assessment: $12,000
At first glance, Townhome B appears to cost $10,000 less.
But once the assessment is included, the difference becomes much smaller.
That's why buyers should calculate the total cost of ownership, rather than comparing listing prices alone.
📅 2. A Special Assessment Can Be Due All at Once—or Over Time
Not every assessment works the same way.
An association may require:
- One lump-sum payment
- Several installments
- A temporary increase in monthly payments
- A combination of payment methods
- Financing through the association
The payment schedule matters.
A $12,000 assessment may feel very different depending on whether the buyer is expected to pay it immediately or over several years.
Before making an offer, find out:
How much is owed?
When is it due?
Who is responsible for paying it?
Does the obligation transfer with the property?
Those questions should be answered in writing by the appropriate professionals.
🧾 3. The Most Important Question: What Is the Assessment Paying For?
The amount alone doesn't tell the entire story.
A $10,000 assessment for a major capital improvement can represent something very different from a $10,000 assessment resulting from an unexpected financial shortfall.
Ask what the assessment is funding.
For example:
Capital Project
The association may be replacing aging roofs throughout the community.
Emergency Repair
A major system may have unexpectedly failed.
Infrastructure Work
Roads, drainage, retaining walls, or other common elements may require significant work.
Reserve Shortfall
The association may not have accumulated enough money for an anticipated project.
The reason behind the assessment can be just as important as the amount.
🏗️ 4. A Special Assessment Can Reveal the Age of the Community
Look at the property beyond the individual unit.
If the community is older, common elements may also be aging.
That can include:
- Roofs
- Siding
- Windows
- Roads
- Parking areas
- Clubhouses
- Pools
- Drainage systems
- Exterior structures
A buyer shouldn't automatically assume that a newer-looking unit means the entire community is in similar condition.
The association maintains many elements that individual owners don't control.
🏦 5. The Association's Reserves Matter
One of the most important financial questions is:
How much money does the association have set aside for future expenses?
A healthy reserve doesn't guarantee that there will never be an assessment.
But reserve planning can provide important context.
New Jersey's Department of Community Affairs explains that condominium associations maintain accounting records that include receipts, expenditures, and unit-level information concerning common expenses and other charges.
For buyers, this reinforces an important point:
The association's financial condition is part of the property you're buying into.
📊 6. Ask Whether There Have Been Previous Assessments
One special assessment deserves investigation.
A pattern of repeated assessments deserves even more attention.
Ask:
- Has the community had recent special assessments?
- What were they for?
- How much were they?
- Were they fully paid?
- Are additional assessments being discussed?
- Have major projects been completed?
- Are there still significant projects ahead?
A history of assessments doesn't automatically mean the association is poorly managed.
Older communities can legitimately require expensive capital work.
But the history can help buyers understand the financial pattern.
🔮 7. Ask About Future Projects—Not Just Current Assessments
This is where buyers need to think beyond the current transaction.
Suppose the association tells you:
“The roof assessment was just completed.”
That's useful.
But then ask:
“What major project is expected next?”
Maybe the community is also planning:
- Siding replacement
- Road resurfacing
- Drainage work
- Pool renovations
- Structural repairs
A recently completed assessment doesn't necessarily mean the community has no significant future expenses.
🏠 8. Condo and Townhome Ownership Can Work Differently
Buyers shouldn't assume that every townhome association works exactly like a condominium association.
In some townhome communities, owners may be responsible for portions of the building or property themselves.
New Jersey DCA guidance notes that fee-simple townhouse developments can have different maintenance responsibilities depending on the association structure and governing documents. Common areas may include features such as parking areas, lawns, pools, or even certain exterior portions of buildings when the association has responsibility for them.
That means buyers need to understand:
What does my association maintain?
And:
What am I personally responsible for?
🔧 9. Exterior Maintenance Can Become a Major Expense
One of the attractions of condo and townhome living is reduced individual maintenance.
But that doesn't mean maintenance disappears.
It shifts.
The association may be responsible for major common elements such as:
- Roofs
- Exterior structures
- Landscaping
- Roads
- Common buildings
- Pools
- Parking areas
When something expensive needs replacement, the association needs a way to pay for it.
That can mean regular reserves, borrowing, increased dues, or special assessments depending on the circumstances.
📈 10. A Low HOA Fee Isn't Always a Bargain
A buyer might see:
HOA fee: $225/month
and think:
“That's great.”
But a low monthly fee isn't automatically evidence of lower ownership costs.
The association still has expenses.
If regular dues aren't sufficient to cover ongoing maintenance and reserve needs, owners may eventually face additional charges.
That's why buyers should compare:
Monthly fee + services + reserves + upcoming projects + assessment history
rather than looking at the monthly fee alone.
🧠 11. Special Assessments Can Affect Your Monthly Budget
Even if the assessment is paid separately, it still affects affordability.
Consider a buyer already budgeting for:
- Mortgage
- Property taxes
- Insurance
- Utilities
- Regular association fees
- Maintenance
- Moving expenses
Adding a $500-per-month assessment installment can materially change the monthly budget.
And if the assessment is due immediately, it can affect the buyer's available cash for closing and reserves.
💵 12. The Assessment Can Change How You Think About an Offer
Suppose a condo is listed at $350,000.
You learn there is an outstanding $15,000 assessment.
That doesn't automatically mean the property is worth $15,000 less.
The assessment could be funding improvements that benefit the community.
The seller may already have paid part of it.
The amount could be allocated differently under the governing documents.
The work could potentially improve the property's long-term appeal.
The important point is:
The assessment becomes part of the negotiation and financial analysis.
Buyers should discuss with their agent and attorney how the assessment should be handled in the contract.
📜 13. Read the Association Documents
Buyers shouldn't rely only on what appears in the listing.
Depending on the community and transaction, buyers may want to review available documents such as:
- Master deed
- Bylaws
- Rules and regulations
- Current budget
- Financial statements
- Meeting minutes
- Reserve information
- Assessment notices
- Pending litigation information where disclosed
- Insurance information
- Recent engineering or inspection reports where available
The exact documents available will vary.
New Jersey's DCA states that association accounting records include receipts, expenditures, and unit-level information regarding common expenses and other charges, and it provides guidance regarding access to those records.
📝 14. Meeting Minutes Can Reveal What the Financial Statements Don't
This is an often-overlooked source of information.
Association meeting minutes can sometimes provide context about:
- Upcoming projects
- Resident concerns
- Maintenance problems
- Contractor discussions
- Budget concerns
- Assessment discussions
- Infrastructure issues
A financial statement might show that the association spent money.
Meeting records may help explain why.
That's why buyers should ask whether relevant association records are available for review.
⚠️ 15. Don't Ignore the Reason an Assessment Was Necessary
Imagine an association recently assessed every owner $8,000 for roof replacement.
The buyer's next question shouldn't simply be:
“How much was it?”
It should be:
“Why was the association not already prepared for this expense?”
There can be perfectly reasonable explanations.
Perhaps construction costs increased dramatically.
Perhaps the roof failed earlier than expected.
Perhaps the community had an unexpected structural issue.
Perhaps reserves were insufficient.
The goal isn't to assign blame.
It's to understand the association's financial and maintenance history.
🏗️ 16. Major Structural Work Deserves Extra Attention
If the assessment involves:
- Structural repairs
- Building envelope problems
- Water intrusion
- Foundation work
- Parking structures
- Retaining walls
- Drainage failures
buyers should understand the scope of the work.
Ask:
- What caused the problem?
- What work is being performed?
- Who evaluated it?
- Has the project been completed?
- What remains?
- Is there additional funding required?
Major common-element work can have implications well beyond the assessment itself.
🛡️ 17. Insurance and Association Finances Can Be Connected
Insurance is another piece of the puzzle.
Associations generally need insurance for covered common property and liabilities, but the exact coverage depends on the community and governing documents.
A buyer should understand:
- What the association's insurance covers
- What the individual owner's policy covers
- Whether there have been major claims
- Whether deductibles have changed
- Whether the association is facing insurance-related cost increases
This is particularly important when an assessment is connected to damage, repairs, or rising operating costs.
🏦 18. Lenders May Care About the Association Too
Buying a condo or certain types of attached housing can involve more than evaluating the individual unit.
The lender may also need information about the project or association.
Questions can involve:
- Association finances
- Insurance
- Pending litigation
- Owner-occupancy
- Delinquent assessments
- Major repairs
- Structural concerns
That's another reason buyers should investigate association issues before getting too close to the closing date.
A problem discovered late can create unnecessary delays.
🔄 19. Special Assessments Can Affect Resale
Think beyond your purchase.
Imagine you're ready to sell several years later.
A future buyer discovers:
“This community has had three assessments in the last five years.”
That history may lead them to ask questions.
Again, assessments don't automatically reduce value.
But buyers tend to care about predictability.
A community with clear financial planning and well-maintained common elements may present a different ownership story than one with repeated unexpected charges.
🧮 20. Calculate the True Cost Before Making an Offer
Instead of asking:
“Can I afford the purchase price?”
ask:
“What will owning this property realistically cost me?”
Consider:
Upfront
- Down payment
- Closing costs
- Initial assessment obligations
- Moving expenses
Monthly
- Mortgage
- Property taxes
- Insurance
- Association dues
- Assessment installments
- Utilities
Future
- Potential increases in association dues
- Major community projects
- Individual maintenance
- Special assessments
- Resale considerations
This gives you a much more realistic picture.
🔎 21. Questions to Ask Before Buying a South Jersey Condo or Townhome
Before making an offer, consider asking:
Assessment
- Is there currently a special assessment?
- How much is it?
- What is it for?
- Has it already been paid?
- When is the remaining balance due?
- Who is contractually responsible for it?
Association Finances
- What are the current monthly dues?
- How much is in reserves?
- Have dues recently increased?
- Have there been previous assessments?
- Are additional assessments being discussed?
Projects
- What major repairs have recently been completed?
- What projects are planned?
- Are engineering reports available?
- Are there unresolved maintenance concerns?
Insurance
- What does the association's policy cover?
- What does the individual owner need to insure?
- Have insurance costs or deductibles changed?
Documents
- Can the buyer review the governing documents?
- Are recent meeting minutes available?
- Are financial statements available?
- Are there notices concerning upcoming projects?
These questions can turn a vague concern into useful information.
⚠️ 22. A Special Assessment Isn't Automatically a Red Flag
This deserves repeating.
An assessment can sometimes mean an association is addressing an important maintenance need.
For example, replacing an aging roof may be expensive—but ignoring the roof could create a much bigger problem.
The better question isn't:
“Does this community have assessments?”
It's:
“How does this community plan, fund, and manage major expenses?”
That distinction matters.
🧠 23. The Bigger Risk Is Uncertainty
A buyer may be comfortable with a $7,000 assessment if they know:
- Exactly what it covers
- When it will be paid
- What work is being done
- Whether the project is funded
- Whether additional charges are expected
What creates more anxiety is:
“We're not sure yet.”
or:
“The board is discussing something.”
or:
“There may be another assessment.”
Uncertainty can make it difficult to understand the true cost of ownership.
💼 How The Murphy Group Helps Buyers Look Beyond the Monthly HOA Fee
At The Murphy Group, the goal is to help buyers evaluate the whole property—not just the listing price and monthly payment.
For condo and townhome buyers, that means encouraging questions about:
- Current assessments
- Association fees
- Community finances
- Planned projects
- Maintenance responsibilities
- Resale considerations
- The total cost of ownership
Mary Murphy explains:
“The monthly association fee is only one part of the financial picture. Buyers need to understand what the association maintains, how it manages major expenses, and whether there are additional costs coming down the road.”
📊 The Bottom Line
A special assessment can change the economics of a South Jersey condo or townhome purchase.
Before making an offer, buyers should understand:
- How much the assessment is
- What it pays for
- When it is due
- Who is responsible for it
- Whether additional assessments are anticipated
- How much the association has in reserves
- What major projects are coming
- How the assessment affects the buyer's total budget
And most importantly:
Don't evaluate a condo or townhome based solely on its listing price and monthly association fee.
The real cost of ownership includes what you're paying today—and what the community may need tomorrow.
A property can still be a great fit with a special assessment.
But you should know about that cost before you make your offer, not after you've already committed to the purchase.
📲 Thinking About Buying a South Jersey Condo or Townhome?
The Murphy Group helps buyers look beyond the listing price and understand the property, association, costs, and questions worth asking before moving forward.
👉 Start here: www.mgsells.com
Mary Murphy
Team Leader | The Murphy Group | eXp Realty, LLC | PLACE
or another way